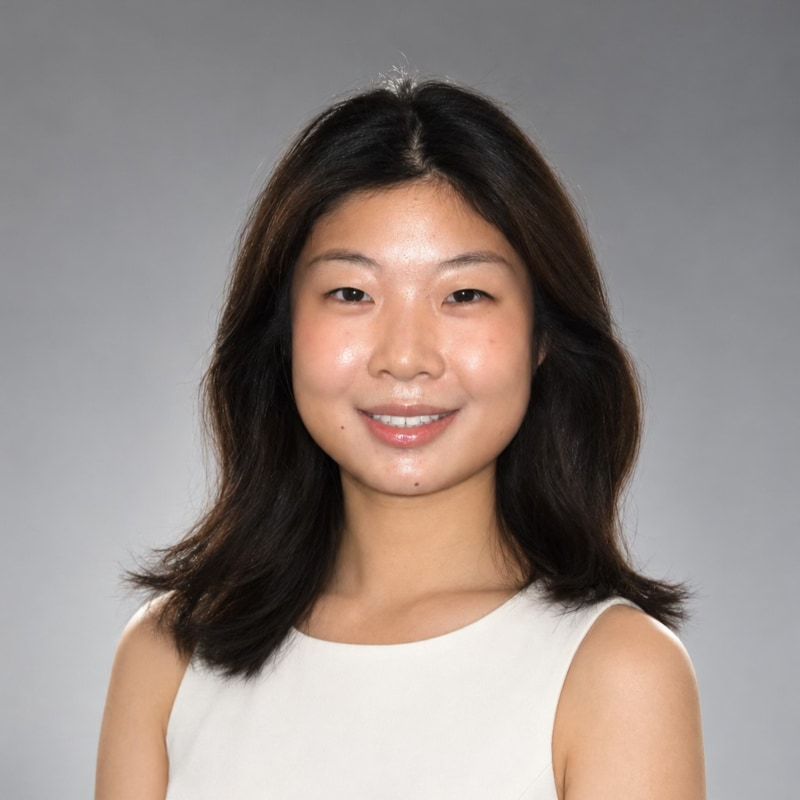
Vanessa Feng

Incoming Analyst at J.P. Morgan in New York. Works on credit and portfolio risk and builds the models behind it. Data Science and Economics at UC San Diego, 2027.

30⁠–⁠35%fewer false positiveson Lima One Capital’s loan watchlist, from a filter she built on its probability‑of‑default model. Recall held above 0.90.

Work

2026

J.P. Morgan

Asset Management Summer Analyst
Jun⁠–⁠Aug 2026, New York

Portrait of Vanessa Feng

2025

Lima One Capital

Credit Risk Intern
Private lender backed by MFA Financial
May⁠–⁠Aug 2025, Greenville, SC

30⁠–⁠35%fewer false positives on the loan watchlist

Piped the probability‑of‑default model into the watchlist as a loan filter, saving about 10 hours of manual review a month.

  • Tested 8 model thresholds against recall, precision, accuracy and ROC‑AUC; chose the one that kept recall above 0.90 with the other metrics at or above firm benchmarks.
  • Built Datarails dashboards that segment about 300 flagged loans a month by product, geography, vintage and sponsor.
  • Restructured the credit approval memo to quantify risk assessments; approval meetings ran about 50% faster.

2025

Morgan Stanley

Wealth Management Intern
Portfolio Risk Management
Aug⁠–⁠Sep 2025, New York

$100MM+of client assets positioned with her Excel forecasts

Tailored model portfolios for six new clients to their risk profiles, liquidity needs and existing exposure, and tested their long-term goals with Monte Carlo simulation.

  • Designed duration- and credit-appropriate fixed income strategies for 10+ client portfolio reviews with the financial planning team.
  • Screened and modelled 10+ US large- and mid-cap stocks; built the Excel forecasts through 2028 that the team used for tactical positioning.
  • Assessed 5 private market funds in infrastructure, real estate and private credit for suitability across 50+ client portfolios.

2024

Rappo

VC Analyst Intern
Tech networking and vendor platform
Jun⁠–⁠Sep 2024, San Francisco

200+investors pitched with the deck she designed

Designed the pitch deck that secured Rappo’s first round of funding.

  • Built a database of 500+ target investors with Python and web scraping, with a risk-appetite scorecard for fit that improved targeting accuracy 50%+.
  • Refined go-to-market from investor feedback; a new one-pager lifted the cold-email success rate 10%+ as Rappo won 100+ clients and $6,000+ in revenue in two months.

2024

Probability of default model

Credit card portfolio
Jan⁠–⁠May 2024, San Diego

300 → 10candidate variables cut to the final model

A logistic-regression model of credit card default. Vintage curves set a 6‑month performance window; roll-rate analysis tracked accounts within it.

  • Narrowed the candidate variables with break-and-heal binning, weight of evidence and information value, stepwise regression and cluster analysis.
  • Set warning and breach thresholds for ongoing monitoring.
Model validation results
KSSeparationPSIStabilityMAPEForecast error
55%0.1310%

Education and credentials

Education

University of California, San Diego

B.S. Data Science and B.A. Economics, 2023⁠–⁠2027. GPA 3.75.

Econometrics, Financial Accounting, Financial Statement Modeling, Data Modeling, Machine Learning & Application, Data Management

Certifications
  • Securities Industry Essentials (SIE)FINRA, 2026
  • Analyzing Financial ReportsWall Street Prep, 2025
  • Excel Skills for BusinessGoldman Sachs, 2024
  • Bloomberg Finance FundamentalsBloomberg
Award
  • The President’s Volunteer Service AwardAmeriCorps, 2021
Languages

English (native), Chinese (native), French (elementary)

Tools

Python, SQL, Java, Snowflake, Tableau, Datarails, Excel, PowerPoint